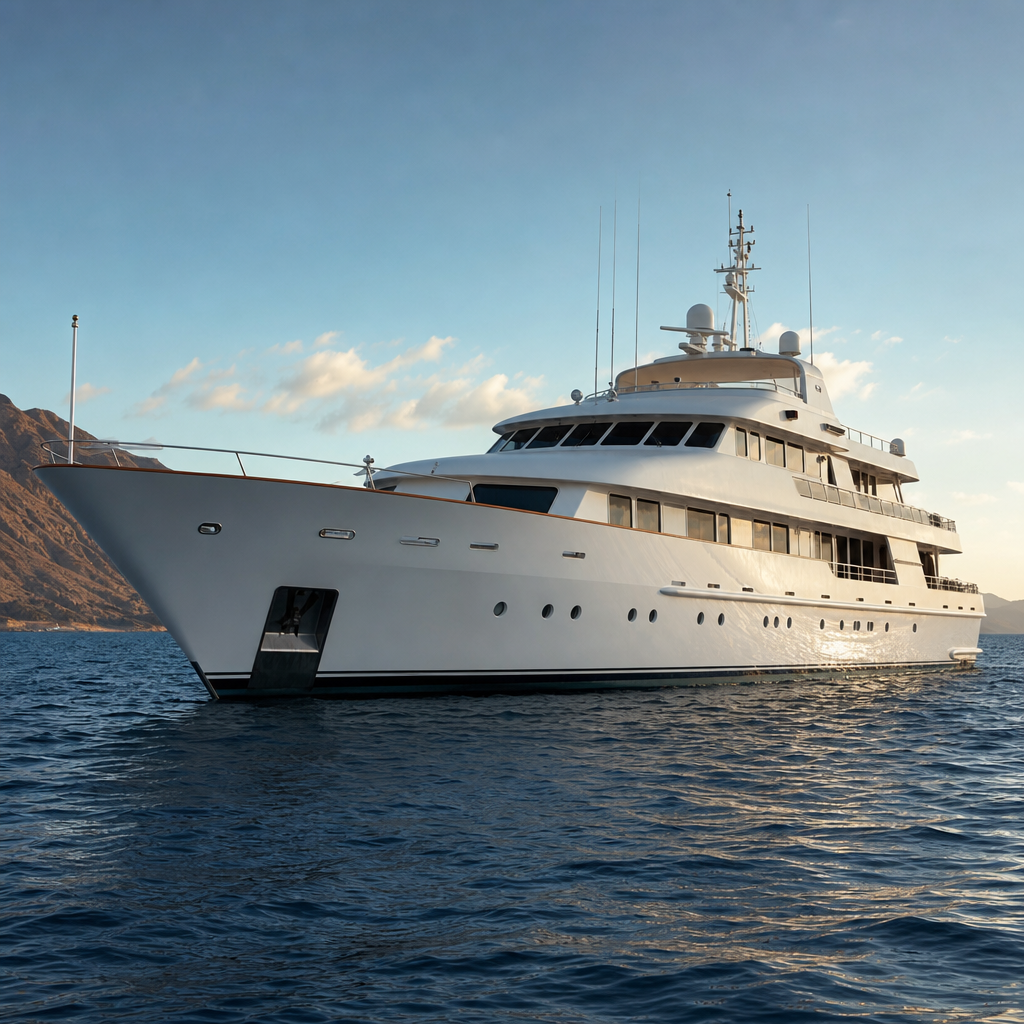
On the morning of 5 November 1991, Robert Maxwell's body was found floating in the Atlantic near the Canary Islands. He had gone overboard from his yacht, the Lady Ghislaine, somewhere in the night. The cause of death was never settled. What happened next, though, was a masterclass in corporate law – whether anyone wanted one or not.
Within weeks, it became clear that Maxwell had looted roughly £460 million from the pension funds of Mirror Group Newspapers and associated companies. Tens of thousands of pensioners suddenly found their retirement savings had effectively vanished. The story dominated the front pages for months, and almost without anyone noticing, it quietly gave the entire British public a working understanding of something lawyers had known since 1855: that a company is not its owner. It is something else entirely.
The Victorian Trick That Nobody Explained
The Limited Liability Act of 1855 was, in its day, a fairly radical idea. Before it, if you started a business and the business failed, your creditors could come after everything you owned – your house, your furniture, the coat on your back. Investors were understandably nervous. So Parliament created a legal fiction: the limited company. It could own things, owe money, and be sued, as a separate legal person in its own right. If it collapsed, the people behind it lost what they had put in, but no more. Their personal assets stayed personal.
This was enormously useful for building railways, funding factories, and generally getting the Industrial Revolution moving. For the best part of a century and a half, though, it was the kind of thing most people never had to think about. You started a business, or you worked for one, or you bought things from one, and the word "limited" on the sign was just part of the furniture.
What the Tabloids Accidentally Taught Us
Maxwell changed that. Because the story his death told – and told at enormous, screaming volume across every front page – was essentially a lesson in how corporate structure works when someone uses it against you.
The pensioners who had lost their savings discovered that Maxwell had not, personally, stolen from them in any simple sense. The money had moved between companies. Mirror Group Newspapers here, Maxwell Communication Corporation there, a web of subsidiaries and holding structures that had their own legal identities, their own assets, their own liabilities. When the structures collapsed, the question of who owed what to whom became a legal labyrinth. The man was dead. The companies were not the man.
For a Cheltenham Boiler Service, visit The Poison That Taught Painting How to Glow
What millions of readers absorbed – through anger rather than study – was the central idea that a limited company is a shield as well as a vehicle. Creditors of the company cannot automatically come after the director's personal bank account. The company's debts belong to the company, and if the company has nothing, those debts die with it, not with the person who ran it. That is the deal Parliament struck in 1855, and it is the deal that still holds.
The Line Maxwell Crossed (And Why It Matters)
The Maxwell story had an important footnote that made the lesson more complete. Because the law does have limits. Directors who knowingly trade while insolvent, or who fraudulently move assets to protect themselves while creditors go unpaid, can be held personally liable. Maxwell's executives faced exactly this scrutiny. Some were disqualified from acting as directors. The protection of limited liability, it turned out, was not a blank cheque – it came with duties attached.
This is why the Maxwell affair left such a lasting mark. It was not just a crime story. It was, in plain language, an explanation of when the company is a wall between you and the consequences, and when that wall comes down. Before 1991, if you had stopped a random person on the street and asked them what "limited liability" meant, most would have shrugged. After two years of Maxwell headlines, an awful lot of them could have told you. Not from a textbook. From the news. From fury.
A Victorian legal invention, designed to encourage railway investors, entered the popular imagination through the death of a bully on a yacht. Which is, frankly, exactly the kind of way Britain tends to learn things.