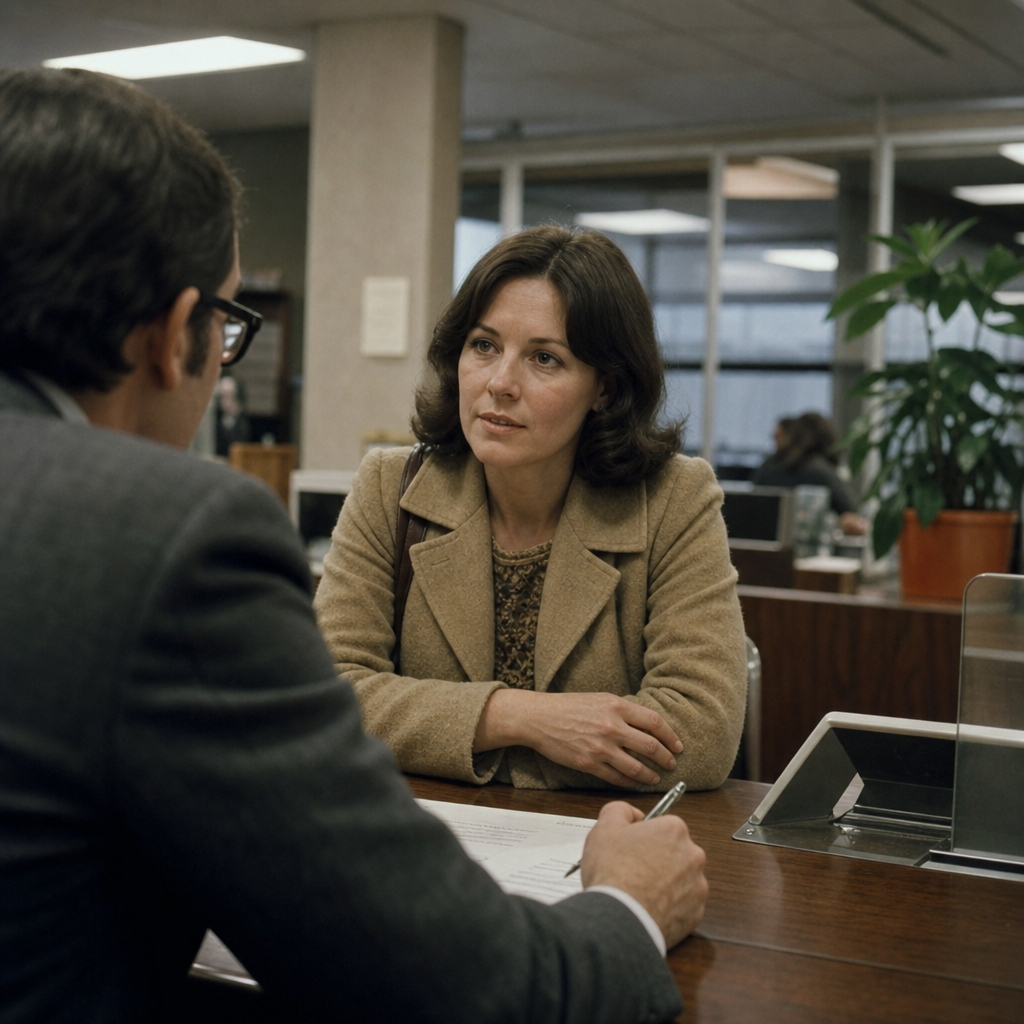
Picture the year 1974. Britain is dealing with a three-day week, power cuts and a particular kind of social chaos. A married woman walks into her local Barclays and asks to open a current account. She sits down with the manager who explains that she will need her husband’s signature for her to open a current account in her name. She is not a child. She has a job. She pays tax. And none of that is quite the point.
This actually happened, routinely, until the Sex Discrimination Act of 1975 made it illegal, but now it’s how most of us use personal finance, with mortgages, credit cards and savings accounts in our own name that require no witness. Most people have no idea that this is not some ancient tradition of fairness but was switched on by specific legislation in specific years and then that was it.
Before the Switch, What Was There?
Archaeologically speaking, what a financial life looked like for half the British population before the mid-1970s was strange. A married woman’s wages legally belonged to her husband until the Married Women’s Property Act of 1882, which helped. But banks were not under any obligation to deal with her as an independent customer. Credit was a husband’s business. A mortgage was a husband’s name. If a woman worked, she often handed cash over at the end of the week and received housekeeping money back – making her more account-holder in the domestic sense than the legal one.
Divorced or widowed women had slightly more ground to stand on. But any lender could simply decline to deal with them without breaking any rule. There was no rule. The idea that a woman should be treated as a creditworthy individual in her own right by a financial institution did not exist as a requirement. It was a courtesy, extended at the manager's discretion.
The Moments That Actually Changed Things
The Sex Discrimination Act of 1975 was the first concrete switch. Banks could no longer legally refuse a woman an account purely because of her sex. Equal Credit Opportunity principles that filtered through in the same era meant that lenders had to assess creditworthiness on income and circumstances, not marital status. Before that, a lender could look at a woman’s salary and mentally file it under ‘pin money’ – temporary, not a real basis for a 25-year mortgage.
The building societies were slower than the banks in practice, and the gap between what was technically legal and what happened at branch level took years to close. A woman applying for a mortgage on her own in 1978 might have met no formal refusal, just an atmosphere of discouragement and a request for a male guarantor (as if this were sensible advice).
If you are in your fifties, your mother experienced this as daily life. If you are younger, there is a reasonable chance your grandmother was navigating it as a working adult.
For a bit of historical context on how recently we've trusted things we assume were always safe, When a Painting Could Kill You makes the same point from a completely different direction.
The Freedoms That Feel Natural But Are Not Old
Rights that come in the form of legislation instead of social change happen quietly and there is no ceremony. One year your manager requires a signature and the following year he does not. Those on the receiving end of the change often have no idea a law has shifted. Instead, they gradually notice that things seem a bit easier.
It's worth remembering this any time personal finance seems like a natural landscape. Mortgages, ISAs, credit scores, joint accounts you can leave. None of it is geological. It is all recent, all constructed, all contingent on specific political moments that could easily have gone differently.
A woman walked into Barclays in 1974 asking for the same unremarkable access to financial life as her husband had had since he turned 18. She had to wait for a law to agree with her before the manager would.
That law is nearly 50 years old now, which is reassuring. But it is not very long at all.